RSS

New 30-Year Amortization & $1.5M Insured Mortgage Rules: What GTA Buyers Need to Know in 2026

​If you’ve been following the GTA real estate market lately, you’ve probably heard a lot about the recent federal mortgage rule changes. The headlines make it sound exciting: more flexibility, easier access to financing, and more options for buyers across Canada. And for many buyers in Ontario—especially first-time homebuyers in the GTA—these updates genuinely can create more opportunities.

​But mortgage rules are only helpful when you understand how they actually affect your budget, monthly payments, and long-term financial goals. That’s where I think the real conversation matters.

​The Reality Check: Buying a home—whether it’s a condo in Mississauga, a townhouse in Milton, or a detached home in Brampton—isn’t about chasing headlines or reacting to market pressure. It’s about understanding your numbers, knowing your options, and making the right move for your family when the timing makes sense for you.

Here’s a practical breakdown of what these new mortgage changes actually mean in Ontario.

​1. The $1.5 Million High-Ratio Insured Mortgage Rule

​One of the biggest updates is the expansion of the high-ratio insured mortgage cap to homes priced up to $1.5 million. For buyers in the GTA, that matters.

​Historically, once a property hit the $1 million mark, buyers needed a minimum 20% down payment. That meant a $1,000,000 home required a $200,000 minimum down payment upfront. For many families in the GTA, especially move-up buyers or younger buyers trying to enter the market, that upfront requirement became the biggest barrier—not the monthly mortgage payment.

​Under the updated rules, eligible buyers can now purchase homes priced between $1 million and $1.5 million with an insured mortgage and a lower required down payment.

​Example: Down Payment for a $1.2 Million Home in the GTA

​The minimum down payment is now calculated on a tiered structure:

  • ​5% on the first $500,000

  • ​10% on the remaining amount up to $1.5 million

​For a $1.2 million home, the shift looks like this:
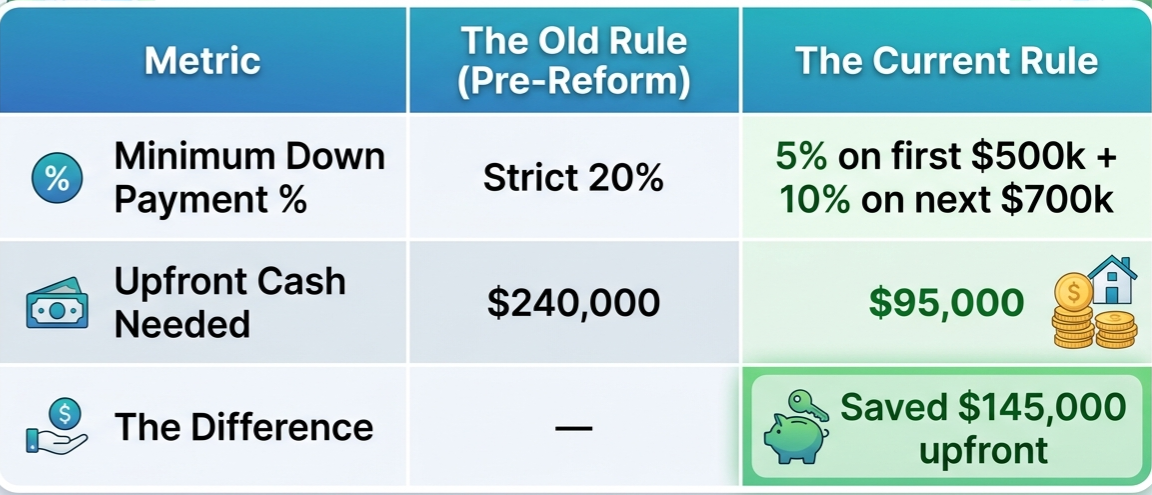
That’s a difference of $145,000 less upfront. It can significantly change what’s possible for buyers looking at townhomes or detached homes in communities like Brampton, Vaughan, Oakville, Burlington, or parts of Durham.

​The Tradeoff: A lower down payment usually means a larger mortgage balance and mortgage insurance premiums added to your financing. It creates flexibility—but it also increases your total borrowing. That’s why it’s worth looking at the full picture before making a move.

​2. The 30-Year Amortization Canada Change

​The second major update is around the 30-year amortization extension in Canada. Previously, buyers putting less than 20% down on an insured mortgage were generally limited to a 25-year amortization.

​Now, eligible buyers can access a 30-year amortization on insured mortgages if:

  • ​You’re a first-time homebuyer in the GTA or anywhere in Canada, or

  • ​You’re purchasing a newly built construction home

​This matters because spreading payments over a longer timeline lowers the required monthly payment. That can improve affordability and may also help with the Canadian mortgage stress test, since lower monthly obligations can support debt ratio calculations.

​25-Year vs. 30-Year Mortgage Comparison

​(Based on a $600,000 mortgage balance at a hypothetical 4.25% interest rate)
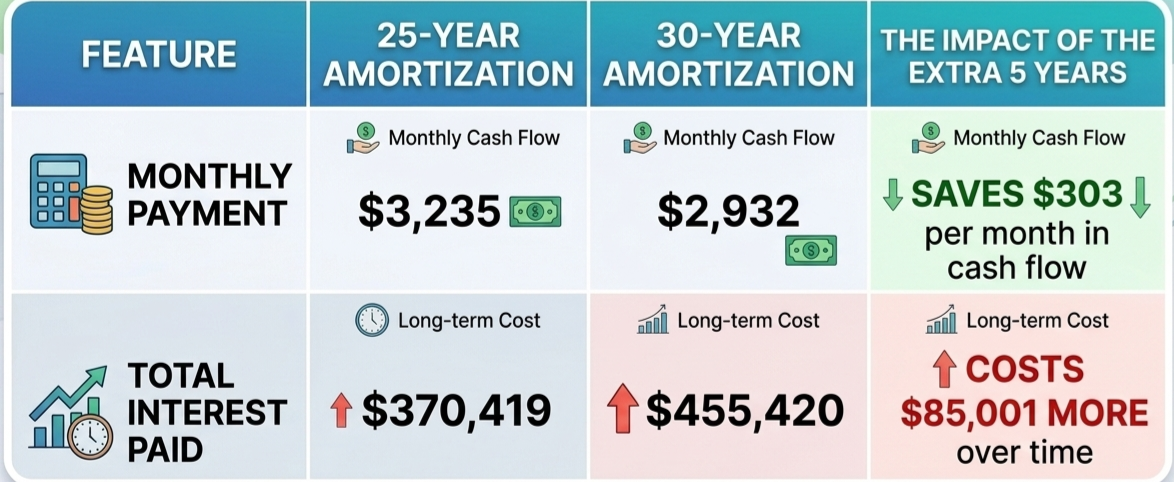
So yes—cash flow improves. But you’re also paying more over time. That’s why this isn’t automatically “better.” It simply gives you another strategy depending on your goals.

​Where This Can Help GTA Buyers Most

​For many buyers in Ontario right now, inventory remains elevated in several markets and negotiation opportunities are still available. That means these mortgage rule changes can be especially helpful for:

  • ​Buyers moving from a condo to a townhouse

  • ​Families looking for detached homes in the suburbs

  • ​Buyers who have strong household income but haven’t saved a full 20% down payment yet

  • ​First-time buyers trying to qualify comfortably while keeping monthly payments manageable

  • ​Buyers purchasing pre-construction or brand-new inventory

​Used carefully, these rules can create more flexibility. And flexibility can be incredibly valuable in a shifting market.

​A Practical Strategy Many Buyers Overlook

​One thing I often remind buyers: a 30-year amortization doesn’t mean you’re locked into paying for 30 years. Most lenders still allow prepayment privileges.

​That means you can:

  • ​Keep the lower required payment now to protect your monthly cash flow.

  • ​Increase your monthly payments or make lump-sum contributions later when your budget allows.

​This approach gives you the safety net of lower mandatory payments today without giving up the ability to pay the mortgage down faster when household income improves. For a lot of families, that balance matters.

​Final Thoughts

​The new $1.5M insured mortgage rules and 30-year amortization Canada changes are meaningful. For some buyers, they may create an opportunity to buy sooner. For others, waiting and continuing to build savings may still be the better move. Neither option is automatically right.

​The goal isn’t to rush. The goal is clarity.

​Understand your budget. Understand the tradeoffs. Understand what ownership looks like beyond the purchase price. And then make your move based on your long-term plan—not market pressure.

​Because the best home purchase decisions in the GTA usually happen when strategy leads first.

From Loan to Home — Your Trusted Path to Ownership. 🏡

Read

Global Uncertainty & The Ontario Housing Market: What Does It Actually Mean for You?

​If you’ve been following the news lately, you’ve probably noticed that global uncertainty seems to be everywhere.

​Ongoing conflicts overseas, rising energy concerns, supply chain disruptions, and persistent inflation pressures continue to dominate headlines. While these events may feel far removed from daily life in Ontario, they have a direct impact on something much closer to home: interest rates, borrowing costs, and housing affordability.

​Many Canadians entered 2026 expecting a series of continuous Bank of Canada rate cuts. Instead, the Bank has maintained its policy rate at 2.25%, with markets watching closely ahead of the next rate announcement on June 10, 2026.

​So what does all of this mean if you’re planning to buy, sell, rent, or invest in Ontario real estate?

​Let’s break it down.

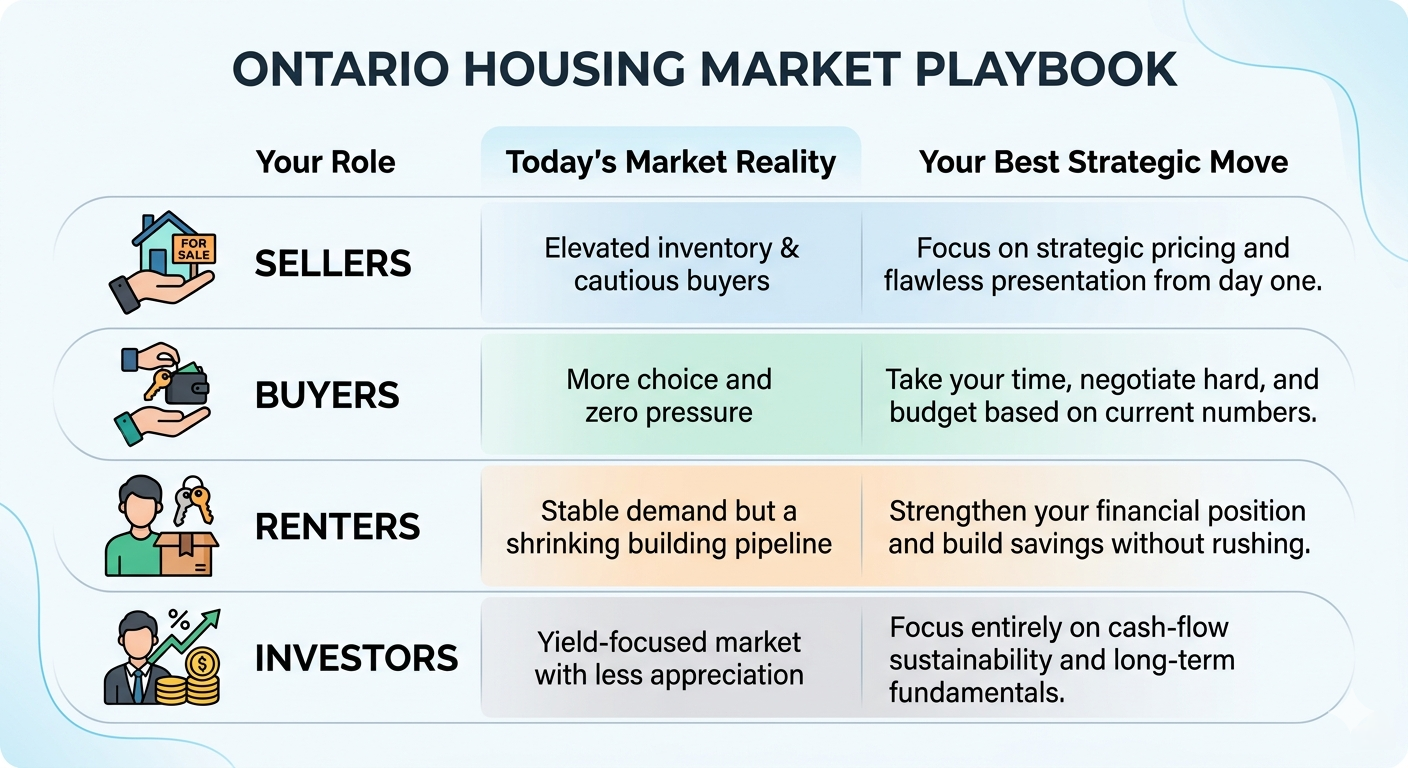
​Sellers: The Market Rewards Strategy, Not Wishful Thinking

​If you’re thinking about listing your home this year, understanding today’s market conditions is critical.

​Inventory levels across many Ontario markets remain elevated, giving buyers more choice than they’ve had in years. While sales activity has improved compared to the slower winter months, prices in many areas remain relatively flat compared to last year.

​What does that mean? Buyers are taking their time.

​They’re comparing properties, negotiating harder, and in many cases, including conditions that would have been almost impossible during the pandemic frenzy. For sellers, this doesn’t mean your home won’t sell. It means proper pricing, strong marketing, and excellent presentation matter more than ever.

​A Quick Reality Check: One of the biggest mistakes a homeowner can make right now is waiting for a sudden spike in prices that may or may not come. If you’re selling and buying within the same market, remember that softer pricing affects both sides of the transaction. The key isn't trying to perfectly time the market—it's understanding the market you are in.

​Buyers: More Choice, More Leverage, Less Pressure

​For buyers, today’s environment offers something that has been missing for several years: breathing room. The fear of being priced out overnight has largely disappeared.

​Yes, borrowing costs remain higher than many buyers would like. Fixed mortgage rates continue to sit in the mid-to-high 4% range because global energy conflicts keep long-term bond yields sticky, while variable-rate borrowers are waiting to see what the Bank of Canada does next.

​But there is a massive silver lining to this equation:

  • ​Stronger Negotiating Power: More inventory means you can finally take the time to review status certificates, complete thorough home inspections, and compare properties.

  • ​Flexible Terms: You can comfortably negotiate terms and protective conditions that would have been rejected immediately just a few years ago.

​The Strategy: Don’t make life-changing decisions based on where you think rates might go. Make decisions based on where your finances are today. If your budget works comfortably at current rates, you can move forward with confidence regardless of what happens next.

​Renters: The Affordability Challenge Isn't Going Away

​Many renters have been waiting for ownership to become significantly more affordable before making a move. Unfortunately, the macro math remains challenging.

​While some recently completed projects have added rental supply in the short term, developers continue to slow new construction activity across Ontario. High commercial financing costs and weaker pre-construction sales have caused many multi-family developments to be delayed or cancelled altogether, pushing housing starts down significantly.

​That creates an important dynamic: The current rental market has stabilized somewhat, but the future pipeline of housing is shrinking. If fewer homes are built today, it can create supply shortages tomorrow.

​The Strategy: For renters who are saving toward homeownership, this is a prime opportunity to focus on strengthening your savings, reducing debt, and improving your mortgage qualification profile rather than rushing into a purchase that stretches your household budget too thin.

​Investors: Cash Flow Matters Again

​The Ontario investment landscape has changed dramatically. For years, many investors relied heavily on rapid appreciation to generate returns, using rising home values to mask weak or even negative cash flow.

​Today’s environment is entirely different. Higher borrowing costs mean that negative cash-flow properties are becoming increasingly difficult to justify, particularly in segments—like the GTA condominium market—where current resale supply remains elevated.

​As a result, smart money is shifting away from speculation and moving toward properties that generate stable, predictable income from day one. The question is no longer: "How much could this property appreciate in two years?"

​The question is: "Does this investment make sense if interest rates stay exactly where they are today?"

​This mindset shift is creating unique opportunities to acquire quality assets at a discount from motivated sellers, provided you focus on fundamentals over guesswork.

​The Bottom Line

​Global events are actively influencing inflation expectations, bond yields, and central bank interest rate decisions. Those factors ultimately filter directly into Ontario’s housing market. But real estate decisions should never be based solely on global headlines.

Nobody knows exactly where rates, prices, or global events will go next. What we do know is that informed decisions consistently outperform emotional ones.

​Whether you’re buying your first home, planning a move, renewing your mortgage, or expanding your investment portfolio, the best strategy is the one built around your unique household goals—not market predictions.

From Loan to Home — Your Trusted Path to Ownership. 🏡
Read

Demystifying Mortgage Default Insurance in Ontario: CMHC, Sagen & Canada Guaranty (2026 Guide)

​Buying a home in Ontario comes with plenty of new terminology—and one of the most misunderstood is mortgage default insurance, often casually called CMHC insurance.

​Many buyers assume this insurance protects them if they miss mortgage payments. In reality, it protects the lender—but understanding how it works can directly impact your mortgage approval, your interest rate, and how much home you can comfortably buy.

​Here’s a straightforward breakdown of how mortgage default insurance works in Ontario.

​What Is Mortgage Default Insurance?

​In Canada, if you purchase a residential property with less than a 20% down payment, mortgage default insurance is generally required. This is called a high-ratio mortgage.

​Because a smaller down payment creates more risk for the lender, the insurer guarantees the mortgage in the event of default. The practical benefit for buyers is that insured mortgages often qualify for lower interest rates than uninsured mortgages.

​That can make a meaningful difference in affordability—especially when navigating the Greater Toronto Area housing market.

​CMHC vs. Sagen vs. Canada Guaranty: What’s the Difference?

​Many buyers use “CMHC insurance” as a catch-all term, but Canada actually has three mortgage default insurance providers. Your mortgage professional will help determine which provider fits your specific financial file best:

​1. Canada Mortgage and Housing Corporation (CMHC)

​Canada’s federal Crown corporation and the most recognized mortgage insurer in the country.

​2. Sagen

​Formerly Genworth Canada, Sagen is Canada’s largest private mortgage default insurer.

​3. Canada Guaranty

​A major, privately owned Canadian mortgage insurer that offers robust alternative programs for diverse buyer profiles.

​While their core premium rates are identical, their underwriting flexibility can differ depending on income type, down payment structure, and unique property details.

​Important Distinction: Mortgage default insurance is entirely different from mortgage life or disability insurance. It protects the lender—not the borrower.

​Who Needs Mortgage Default Insurance in Ontario?

​Mortgage default insurance typically applies when your down payment is between 5% and 19.99%. To qualify, insured mortgages must meet strict federal guidelines:

​Maximum Purchase Price

​Homes purchased for under $1.5 million may qualify for insured financing. Properties at $1.5 million or more automatically require a conventional mortgage with a minimum 20% down payment.

​Down Payment Tiers

​The minimum down payment in Canada is calculated progressively based on the purchase price:

  • ​5% on the first $500,000

  • ​10% on the portion between $500,000 and $1,499,999

Example Calculation: On a purchase price of $900,000:

  • ​First $500,000 = $25,000

  • ​Remaining $400,000 = $40,000

  • ​Minimum required down payment = $65,000

​Amortization Rules

​The standard maximum amortization for insured mortgages is 25 years. However, a 30-year amortization is available to help lower monthly payments under two specific exceptions:

  1. ​You are an eligible first-time homebuyer.

  2. ​You are purchasing an eligible newly built home.

​Occupancy Rules

​The home must be located in Canada and intended as an owner-occupied property (or occupied by an immediate family member on a rent-free basis).

​How Much Does Mortgage Default Insurance Cost?

​Insurance premiums are calculated as a percentage of your total loan amount and are based entirely on your Loan-to-Value (LTV) ratio

Note: If you qualify for and choose a 30-year amortization, a small premium surcharge of 0.20% is added to the standard rates above.

Example Scenario:

​Purchase price: $700,000

​Down payment: 10% ($70,000)

​Mortgage amount before insurance: $630,000

​Estimated premium at 3.10% = $19,530

​This premium is added directly to your principal mortgage balance, meaning you pay it down gradually over time rather than upfront.

Ontario Closing Cost Detail: PST on the Insurance Premium

​A detail many Ontario buyers miss during their budgeting phase: while the premium itself is rolled into the mortgage, Ontario’s 8% Provincial Sales Tax (PST) applies to the premium and must be paid in cash at closing.

​Using the example above:

  • ​Premium = $19,530

  • ​Ontario PST due on closing = $1,562.40

​This amount needs to be budgeted explicitly as part of your out-of-pocket closing costs.

​Step-by-Step: How Do You Qualify for CMHC, Sagen, or Canada Guaranty?

​Insurers look beyond just your annual income—they assess the overall strength and stability of your financial file:

Ontario Buyers: Why This Matters

​Mortgage default insurance can feel like an extra expense—but for many buyers, it acts as a valuable tool that unlocks:

  • ​Lower down payment requirements, keeping more cash in your reserves.

  • ​Stronger, highly competitive mortgage interest rates.

  • ​An earlier entry point into the Ontario real estate market.

​For buyers across the Greater Toronto Area—including Brampton, Mississauga, Milton, and Whitby—understanding these guidelines before you start shopping can save substantial stress and help you build a clear, bulletproof budget.

​Whether you’re buying your first home, moving up to a larger property, or comparing insured vs. conventional financing, understanding mortgage default insurance early helps you make better decisions—and avoid surprises on closing day.

From Loan to Home — Your Trusted Path to Ownership. 🏡

Read

Is the GTA Buyer’s Window Starting to Close? The Rate vs. Price Reality Check

​If you’ve been waiting for mortgage rates to drop before buying a home in Ontario, you’re not alone. A vast majority of intending buyers across the Greater Toronto Area are watching the Bank of Canada and waiting for lenders to give them the green light.

​But here’s the real question you should be asking yourself: Are you giving up thousands of dollars in negotiating power just to save a fraction of a percent on your mortgage rate?

​Right now in the GTA, the true window of opportunity has less to do with rates—and everything to do with inventory, options, and buyer leverage.

​Current GTA Housing Trends: A Rare, Buyer-Friendly Window

​For the first time in years, buyers across the GTA have real breathing room. According to the latest data from the Toronto Regional Real Estate Board (TRREB), the average selling price across the GTA is holding steady at $1,051,969.

​While the spring market has brought a steady uptick in sales, we are still operating in a landscape defined by healthy inventory levels. Homes are taking longer to sell, sellers are significantly more flexible, and many buyers finally have the ability to negotiate with protective conditions and take their time.

​That matters immensely.

​Because not long ago, buyers were trapped in frantic multiple-offer bidding wars, waiving home inspections, and making rushed, high-stress decisions just to get a foot in the door. Today feels entirely different.

​📍 Where Buyers Are Seeing Opportunity Right Now

​The current market isn't uniform; it's highly regionalized. If you know where to look, specific pockets of the GTA are offering incredible strategic advantages:

​Peel Region & Brampton

​There is a great selection of detached homes and semi-detached properties hitting the market. This is an ideal setup for growing families who want to weigh their options carefully without feeling rushed or outbid over a single weekend.

​Scarborough

​Solid entry-level opportunities are appearing in the townhouse and condo sectors. Because these segments have seen higher inventory buildup, sellers here are often much more open to serious price negotiations and flexible closing terms.

​York Region & The North GTA

​Move-up buyers are benefiting from longer days on market. This slower pace creates the necessary room for proper due diligence, thorough home inspections, and stronger contract positioning.

​The Math: Rate vs. Price Reality Check

​When buying real estate, you are always balancing two core numbers: your purchase price and your mortgage rate. A lot of buyers focus exclusively on the rate—but the purchase price matters just as much, if not more, over the long term.

A lower interest rate can certainly help your monthly cash flow today. But paying a premium for the property because you bought during a market surge can cost you far more over the lifespan of your mortgage.

The Long-Term Financial Reality: Mortgage rates are variable over time. You can refinance later, switch lenders at renewal, or restructure your mortgage strategy down the road when rates drop. But the purchase price you pay for the property today is completely permanent—it becomes the baseline of your long-term financial picture.

Why This Matters Right Now

​Across Brampton, Mississauga, and many key GTA suburbs, we are seeing a unique combination of market factors that simply do not stay around forever:

  • ​Sellers are adjusting expectations to match realistic market values.

  • ​Buyers are successfully negotiating price reductions and seller concessions.  

  • ​Standard protective conditions are back in the Agreement of Purchase and Sale.  

  • ​There is actual room to compare properties and make smart, calculated decisions.

​Once consumer confidence fully returns and the general public floods back into the market, this window of leverage will disappear quickly. By the time everyone feels "perfectly comfortable" to buy, the best opportunities are usually gone.

​If you’re thinking about buying a home in the GTA this year—whether it’s Brampton, Mississauga, Vaughan, or another local neighbourhood—this is the time to look at what’s available and see what kind of negotiating power you actually possess.

​Let's Map Out Your Strategy

​📩 Reach out anytime. We can review your target neighbourhoods, analyze current active listings, analyze your mortgage options, and map out the numbers together to ensure you're making a move that protects your wealth.

From Loan to Home — Your Trusted Path to Ownership. 🏡

Read

​Why Canada’s 2026 Housing Construction Slowdown Could Actually Be Your Buying Window 🏡

​If you’ve been following the real estate headlines lately, it’s easy to feel a little uneasy.

​Canada recently reported a slowdown in building construction investment, and Ontario has been seeing some of the biggest declines in residential construction. At the same time, the Canada Mortgage and Housing Corporation (CMHC) is warning that housing starts could remain slower through 2028—especially in the condo market.

​And on the surface, that sounds concerning. Less construction usually makes people think “less inventory” and “higher prices.”

​But when I look at it through both the mortgage and real estate lens, I actually see something very different. For buyers and investors across the Greater Toronto Area, this isn’t necessarily bad news. It could actually be one of the better buying opportunities we’ve had in years.

​More Breathing Room for Buyers

​For a long time, buying in Ontario felt exhausting. Homes were moving fast, bidding wars were intense, and buyers often felt pressure to make huge decisions with very little time.

​That energy has shifted. As developers slow down on new condo launches and pre-construction projects, resale inventory has become more balanced.

​That matters, because buyers finally have something we haven’t seen much of lately:

  • ​✔️ More options

  • ​✔️ More negotiating power

  • ​✔️ More time to think before making an offer

​And maybe most importantly—buyers are able to protect themselves again. We’re seeing financing conditions and home inspection clauses make a real comeback. That gives buyers confidence and helps avoid costly surprises.

​Prices Feel More Predictable

​Another big change? Pricing feels much steadier.

​Instead of the dramatic swings we saw over the last few years, many parts of the GTA are moving in a more balanced way. For buyers, that can feel like a huge relief.

​You can actually plan. You can compare homes properly. You can negotiate based on real numbers instead of reacting to panic and competing blindly. That kind of stability makes decision-making so much easier.

​The Mortgage Side Matters Too

​From the financing side, this environment has become a lot more predictable too. The Bank of Canada holding rates steady has created more consistency for buyers budgeting for a purchase.

​And predictability matters. When rates are moving aggressively every few weeks, buyers hesitate. When rates feel more stable, it becomes easier to:

  • ​Lock in a pre-approval

  • ​Understand monthly payments

  • ​Stress test properly

  • ​Compare fixed vs. variable with confidence

  • ​Negotiate knowing your budget is solid

​That makes a big difference when you’re house hunting.

​Why Resale is Getting More Attention in 2026

​With condo starts slowing across the Greater Toronto Area, more buyers are naturally looking at resale homes. And I understand why.

​A resale home gives you clarity:

  • ​You can physically see the property.

  • ​You can review the hard numbers.

  • ​You can get it professionally inspected.

  • ​You know exactly what your closing looks like.

  • ​You know exactly what your mortgage approval looks like.

​Best of all, you can move forward based on today’s values—not guessing what rates or prices may look like 3 or 4 years from now. That certainty feels very valuable right now.

​The Bottom Line

​Long term, Canada absolutely needs more housing. That part is true.

​But short term? This slowdown is creating a window buyers haven’t had in a while. It means a more balanced market, less pressure, better negotiating opportunities, more protection, and a real chance to buy with a strategy instead of rushing.

​Let's Build Your Strategy

​If you’ve been sitting on the sidelines waiting for the “perfect” moment, it may be worth taking another look at what’s happening right now in Ontario. There may be more opportunity here than the headlines are showing.

​✨ Thinking about buying in the GTA or anywhere in Ontario this year? Let’s look at your numbers, explore your options, and build a strategy that makes sense for you.

From Loan to Home — Your Trusted Path to Ownership. 🏡

Read

The Pre-Construction Rescue Plan: What to Do If You Can’t Close in Ontario 🏗️🏡

​Bought a pre-construction condo or townhouse in Ontario a few years ago and feeling stressed about your upcoming closing date? You’re definitely not alone—and walking away may not be your only option.

​A lot of buyers who signed pre-construction contracts three or four years ago are now facing a completely transformed real estate market.

​Property values have shifted, interest rates are higher than expected, and the backup plan of executing an assignment sale before final closing has stalled. Because assignment buyers simply aren’t moving the way they were a few years ago, inventory is piling up, leaving many contract holders feeling completely stuck.

​That leaves many people facing a difficult reality: find a way to close and come up with extra funds… or risk losing a large deposit and potentially being pursued legally by the developer.

​Before making a rushed decision, it’s important to know that you still have options to protect your capital and stabilize your investment.

​The Biggest Challenge Right Now: The Pre-Construction Appraisal Gap

​The most common hurdle in Ontario real estate closings today is the appraisal gap.

​When you apply for a mortgage on a new build, a traditional lender bases their financing on what the property is worth today—not the original purchase price you agreed to and initialled in your contract years ago.

If your bank appraises the property at $730,000, they will only lend you a percentage of that lower number. You are suddenly required to cover the $70,000 shortfall yourself, on top of your standard closing costs, legal fees, and provincial land transfer taxes.

​Worse yet, many pre-construction buyers are blindsided at final closing by un-capped builder development charges and Tarion enrolment fees on their final statement of adjustments. For many buyers, this cumulative shortfall is where the panic starts.

​Can You Use Private Financing for a Pre-Construction Closing?

​A traditional bank declining your mortgage application does not mean your real estate deal is over. This is precisely where alternative lending (B-lenders) and private financing can serve as a critical short-term bridge.

​Depending on the property and your equity position, securing an alternative or private mortgage extension can safely get you across the finish line and prevent an immediate default.

​The Strategy: Treat a 1-year alternative mortgage as a short-term stabilization window. It gives you a 12-month runway to protect your initial investment while you adjust your long-term plan.

​This extra 12 months creates the breathing room needed to:

  • ​Close and protect your deposit from being completely forfeited to the builder.

  • ​Rent the property immediately to offset your monthly carrying costs.

  • ​Improve your debt ratios or income positioning without intense timeline pressure.

  • ​Refinance later with a traditional prime lender when the numbers or your financial profile align.

  • ​Give the market time to stabilize so you aren't forced to sell your contract at a deep loss during a temporary dip.

​Shifting From a "Quick Flip" to a Long-Term Investment Hold

​Many buyers originally purchased pre-construction units with the intention of executing a quick flip before final closing. In the current Greater Toronto Area (GTA) market, that layout isn't realistic for everyone.

​For many, the smartest financial move is pivoting the property into a long-term investment instead.

​Even if carrying the property feels tight for a temporary period, preserving a $100,000+ deposit and retaining control of a tangible asset puts you in a vastly superior financial position compared to walking away and losing everything you’ve invested.

​Across the GTA, long-term rental demand has remained active. Building a clear leasing plan allows you to leverage rental income to carry the asset while the macroeconomic cycle repositions in your favour.

​What Happens If You Walk Away From a Pre-Construction Contract?

​The single biggest mistake a buyer can make is waiting too long to evaluate their options. If your closing date is coming up in the next 3 to 6 months, you need to review your numbers, financing alternatives, and appraisal risks right now.

​Walking away should always be your absolute last resort.

​Builders across Ontario are taking defaults incredibly seriously. Under Canadian real estate law, if a buyer defaults and the builder is forced to resell the unit at a lower price to someone else, the builder can legally sue the original buyer for the entire price difference, plus extra interest, marketing expenses, legal fees, and carrying costs.

​A plan made early gives you flexibility, alternative lending choices, and control. A plan made under pressure usually costs more.

​Get a Strategy Session for Your Upcoming Closing

​If you have an Ontario pre-construction closing approaching and you are unsure how the final financing will line up, do not let the clock run out on your deposit. Sometimes, a second opinion and a clear alternative lending strategy are all it takes to turn a financial crisis into a managed, successful investment.

​Reach out today for a confidential Pre-Closing Strategy Session. We will review your original agreement of purchase and sale, analyze your current appraisal risk, and map out a clear roadmap to get your deal safely across the finish line.

From Loan to Home — Your Trusted Path to Ownership. 🏡

Read

10 Ways to Accidentally Kill Your Deal (Buyer & Seller Edition) 🏡❌

You’ve signed the Agreement of Purchase and Sale, the deposit is in, and now you’re counting down the days until closing. But here’s what a lot of people don’t realize…

A deal isn’t officially done until the money changes hands and the property is registered.

Between acceptance and closing day, there are a lot of moving parts — and one mistake from either the buyer or seller can delay the deal, create legal issues, or even cause the transaction to fall apart completely.

Here are 10 common ways deals get accidentally killed 👇

🛑 For Buyers:

1️⃣ Getting stuck on small inspection items
Don’t let a deal fall apart over tiny repairs or cosmetic issues. Asking for every little thing to be fixed can quickly turn negotiations sour.

2️⃣ Waiting too long to arrange home insurance
Certain homes can be harder to insure than people think. If insurance becomes an issue right before closing, your financing can get delayed too.

3️⃣ Changing your finances before closing
Buying a car, switching jobs, missing payments, or moving large amounts of money around can impact your mortgage approval — even after you’re pre-approved.

4️⃣ Skipping the final walkthrough
Your final visit is your chance to make sure the home is still in the condition you agreed to buy it in. It’s important — but refusing to close over something minor can create bigger problems too.

5️⃣ Forgetting about closing costs
Your down payment isn’t the only expense. Legal fees, land transfer tax, title insurance, adjustments, and other costs add up quickly.

🛑 For Sellers:

6️⃣ Removing included items from the home
If appliances, light fixtures, or other items were included in the contract, they need to stay. Taking them out last minute can create major issues.

7️⃣ Not maintaining the property before closing
The home needs to stay in substantially the same condition until closing day. New damage, neglect, or ignored issues can put the deal at risk.

8️⃣ Leaving title or lien issues until the last minute
Outstanding taxes, liens, or title problems can delay or completely stop a closing if they aren’t handled early.

9️⃣ Making access difficult for appraisals or visits
Buyers, appraisers, and inspectors may need access before closing. Delays and constant rescheduling can impact financing timelines.

🔟 Letting emotions take over
Whether it’s buyer’s remorse or seller’s remorse, once the contract is signed both parties have legal obligations. Making the process difficult rarely ends well.

📌 Bottom Line:

A smooth closing comes down to preparation, communication, and having the right people guiding you through the process.

Whether you’re buying or selling in Ontario, having a strong team around you can help prevent small issues from turning into deal-breaking problems.

Thinking about making a move this year? Reach out anytime — I’m always happy to help. 📲

From Loan to Home — Your Trusted Path to Ownership. 🏡

Read

10 Ways to Accidentally Kill Your Closing (And How to Avoid It) 🏡🚫

​You found the house, got the offer accepted, and now you’re counting down the days until you get the keys. But here’s the part a lot of buyers don’t realize…

​Your mortgage still isn’t fully safe until closing day.

​Lenders continue reviewing your finances right up until the deal closes, and even small changes can create delays or completely derail your approval.

​Here are 10 things you should avoid during the closing process:

​1️⃣ Don’t finance furniture or appliances

I know it’s tempting to start shopping for the new house, but new debt can change your approval numbers fast.

​2️⃣ Don’t switch jobs

Even a better job or different pay structure can create extra conditions with the lender. Maintain employment stability until the keys are in your hand.

​3️⃣ Don’t move money around unnecessarily

Large transfers between accounts can create red flags and require extra paperwork to satisfy underwriters.

​4️⃣ Don’t deposit large amounts of cash

If the lender can’t properly track and source exactly where the money came from, it can become a major issue for your down payment approval.

​5️⃣ Don’t co-sign for anyone

Even if you’re just helping a family member out, that debt now legally counts against your own borrowing capacity.

​6️⃣ Don’t let your credit score slip

Missed payments or high balances right before closing can hurt your final approval. Lenders will do a final credit check.

​7️⃣ Don’t apply for new credit

No new credit cards, car loans, or lines of credit until after you close. Keep your credit profile frozen.

​8️⃣ Don’t disappear during closing week

Your real estate and mortgage team, or your lawyer, may need documents quickly. Delays in communication can push back your closing date.

​9️⃣ Don’t switch insurance providers last minute

Changing home insurance policies late in the process forces the lender to rewrite paperwork, delaying final mortgage documents.

​🔟 Don’t underestimate closing costs

Legal fees, land transfer taxes, title insurance, and property tax adjustments add up quickly. Always keep a financial cushion.

​📌 The best thing you can do before closing?

Keep everything stable — your job, your credit, and your bank accounts.

​A smooth closing isn’t just about getting approved… it’s about staying approved.

​If you’re planning to buy, refinance, or renew and want to make sure you’re set up properly from the start, reach out anytime.

From Loan to Home — Your Trusted Path to Ownership. 🏡

Read

Has the GTA Condo Market Finally Hit Rock Bottom?

If you’ve been watching the GTA condo market over the last couple of years, you already know it’s been a rollercoaster.

After the peak in early 2022, condo prices took a noticeable hit. Buyers got cautious, investors stepped back, and uncertainty started driving the conversation.

But now in 2026, the big question is: Have we finally hit the bottom?

The truth? Nobody rings a bell at the exact bottom of a market. But when you look at the numbers, the policy changes, and what’s happening behind the scenes with supply, there are strong signs that we’re operating in the “trough” of this cycle.

And historically, that’s where opportunities are created.

What the Current GTA Condo Market Is Telling Us

The latest TRREB numbers are starting to paint a different picture than what we saw over the last 18–24 months.

🔹 Condo prices are stabilizing.
The average GTA condo apartment is sitting around $635,653. While prices are still down year-over-year, we’re now seeing month-over-month gains again — a sign the market may be finding its footing.

🔹 Buyer activity is picking up.
Sales activity has started climbing as buyers take advantage of softer pricing, more inventory, and slightly improved borrowing conditions.

🔹 Resale condos are creating real opportunities.
Right now, resale is where the value is. Many condos are still trading well below peak pricing, giving buyers and investors a much more approachable entry point compared to pre-construction.

Why This Market Feels Different

1. The Numbers Are Starting to Make Sense Again

At the peak of interest rates, many condo investors were bleeding cash every month just to hold a property.

Now? Between adjusted prices and stabilized rental rates, the math is becoming much more manageable again.

For long-term buyers, that matters.

A properly structured purchase today can position someone far better than chasing the market later when prices and competition inevitably heat back up.

2. Government Policy Is Supporting Housing

We’ve also seen multiple levels of government step in with affordability measures, tax relief, and incentives aimed at stimulating housing activity.

Whether people agree with every policy or not, one thing is clear: there’s significant pressure to support housing stability in Ontario.

That creates an important psychological floor for the market.

3. The Biggest Story Nobody Is Talking About: The Supply Cliff

This is the piece most buyers are missing.

Because pre-construction sales slowed dramatically over the last two years, fewer projects moved forward. And condo developments don’t appear overnight — they take years to complete.

That means while we’re still absorbing projects launched during the 2021–2022 frenzy, new inventory is expected to slow down significantly by 2027 and beyond.

Less future supply + returning demand = upward pressure on pricing.

That’s just economics.

The Reality About Waiting

A lot of buyers are still sitting on the sidelines waiting for certainty.

But certainty usually comes at a premium.

Once headlines start saying “the market is back,” the leverage buyers currently have disappears fast. Inventory tightens, competition returns, and conditions start disappearing from offers again.

Right now, buyers still have:

 ✔️ Negotiating power
✔️ Inventory to choose from
✔️ Time for due diligence
✔️ Less emotional competition

That’s a very different environment than what we saw during peak market conditions.

So… Is Now the Right Time to Buy?

If you’re looking for a quick flip or short-term gains, this market still carries volatility.

But if you’re a first-time buyer trying to stop renting, or a long-term investor thinking 5–10 years ahead, this may be one of the strongest buying windows we’ve seen in years.

The market is resetting — not collapsing.

And historically, the people who make the best long-term moves are usually the ones buying during the quieter phases of the cycle, not after the headlines turn optimistic again.

What’s your take on the GTA condo market right now?

Are you waiting for rates to drop further, or are you already exploring opportunities in the resale market?

If you want to break down the numbers for a specific building or neighbourhood in the GTA, give me a call — let’s look at the math and see what opportunities make sense for your goals.

From Loan to Home — Your Trusted Path to Ownership. 🏡

Read

Market Timing vs. Market Time: Should You Wait for the 2027 Ontario Housing Market?

​Right now, many buyers across Ontario are sitting on the sidelines thinking the same thing: “If prices dip a little more in 2027, maybe I should just wait.”

​Honestly? I understand the thought process. With the 2026 Ontario real estate market showing more inventory, softer pricing, and less competition than we’ve seen in years, it’s tempting to think the “perfect moment” is still months away.

​But here is the part many overlook: The best opportunities in Real Estate usually happen when buyers have options—not when everyone rushes back into the market at the same time.

​What the 2026 Ontario Market Actually Looks Like

​Across the Greater Toronto Area (GTA) and broader Ontario, we are seeing a rare window of opportunity. According to current data, home prices in several regions have corrected by 6–8%, creating a "Goldilocks" zone for end-users.

​For buyers today, this shift means:

  • ​Increased Inventory: More homes to choose from without the "fear of missing out."

  • ​Negotiating Power: You finally have the leverage to discuss price and terms.

  • ​Due Diligence: The ability to include financing and home inspection conditions—protections that were nearly impossible to include two years ago.

  • ​Less Pressure: You can make a calculated decision rather than an emotional one.

​The Problem With Waiting for the “Bottom”

​The challenge with trying to time the market is that nobody rings a bell when the bottom officially arrives.

​The recent CMHC (Canada Mortgage and Housing Corporation) Housing Market Outlook suggests that while 2026 is a period of stabilization, demand is expected to strengthen significantly moving into 2027. When that "pent-up demand" breaks, the market shifts instantly.

​Once buyers re-enter the market en masse:

  1. ​Inventory starts shrinking rapidly.

  2. ​Your negotiation power disappears.

  3. ​Bidding wars return, often driving prices up higher than the "savings" you were waiting for.

​Calculating the Real “Cost of Waiting”

​While many focus on the purchase price, waiting for 2027 carries hidden financial risks:

  • ​Equity Loss: Another year of paying rent is 100% interest; you aren't building wealth.

  • ​Interest Rate Volatility: Even a small dip in price can be canceled out by shifts in mortgage qualifying rules or rates.

  • ​The Lifestyle Delay: You can't put a price on another year spent in a home your family has already outgrown.

​Why 2026 is the Year of the "Power Buyer"

​The strongest homeowners aren’t usually the ones who timed the bottom perfectly. They’re the ones who bought when they had choices.

​In the current 2026 market, you have something incredibly valuable: Time. Time to compare, time to negotiate, and time to protect your investment. In a "hot" market, that luxury disappears in hours.

​Final Thoughts

​If your goal is to chase a theoretical "lowest price," waiting might feel safer. But if your goal is long-term wealth building and securing the right lifestyle for your family, the 2026 window offers the most balanced environment we’ve seen in a decade.

​You don’t build wealth by timing the market; you build it by having time in the market.

From Loan to Home — Your Trusted Path to Ownership. 🏡

Read

Status Certificate “Red Flags”: How to Avoid a $50,000 Surprise in the GTA Condo Market

​As of May 2026, the GTA condo market is in a unique spot. Prices have adjusted—we’re seeing averages across the region hovering around $620,000—but maintenance fees? They’re climbing faster than ever.

​If you’re condo shopping in Toronto, Mississauga, or anywhere in the 905, the most important document isn’t the floor plan or the lake view… it’s the Status Certificate. This is the only way to catch a building's problems before they become your financial nightmare.

​Here’s how I tell my clients to break it down. 

​1. Your Quick “Red Light / Green Light” Check

​Think of the Status Certificate as a medical report for the building. Before you dive into the hundreds of pages of bylaws, check these vitals:

2. The Reserve Fund Study: The Building’s Savings Account

​Every condo building in Ontario is legally required to conduct a Reserve Fund Study (RFS) every three years. This document tells you:

  • ​➡️ What major repairs are coming (Roof, elevators, parking garage).

  • ​➡️ How much those repairs will cost.

  • ​➡️ Whether the building actually has the cash to pay for them.

​The 2026 Trap: 

Many newer buildings launch with low maintenance fees to attract buyers. But because construction inflation has skyrocketed in the last few years, many of these buildings are underfunded from Day 1. By Year 5, you either see fees jump by 30% or the owners get hit with a massive bill.

​What to check: Does the actual cash in the bank match what the study says it should be right now? If there’s a gap, that bill doesn't disappear—it gets passed to you.

​3. Special Assessments (The One Everyone Wants to Avoid)

​A Special Assessment is a mandatory, one-time payment from owners to cover a budget shortfall. In today’s market, these aren't small "service fees." We are currently seeing:

  • ​➡️ $15,000 for window seal failures.

  • ​➡️ $30,000 for parking garage membranes.

  • ​➡️ $60,000+ for major structural or balcony overhauls.

​One thing most people overlook: Keep an eye on empty ground-floor retail units. If those commercial spaces are vacant, that lost income can shift the building's operating costs directly onto the residential owners.

​4. Why “Cheap” Condos Can Cost You More

​If a condo looks like a total steal, there is almost always a reason. In the current GTA market, we see a recurring pattern:

  • ​Lower purchase price ➡️ High maintenance fees ($1.10+ per sqft) ➡️ Or a looming $40k assessment.

​The Mortgage Impact:

High maintenance fees directly hit your "Buying Power." If you’re paying $900/month in fees, a bank will qualify you for roughly $40,000 to $50,000 less in mortgage principal than a building with $500 fees.

​The Final Take

​There are definitely opportunities in the GTA condo market right now—but only if you do your homework. The biggest mistake you can make in 2026 is waiving the Status Certificate condition.

​Don't just look at the finishes; make sure your Realtor and lawyer are digging into:

  • ​✔️ Reserve fund health vs. actual bank balance.

  • ​✔️ The 30-year funding plan.

  • ​✔️ Any signs of upcoming major construction.

​The goal isn’t just to buy a condo; it’s to avoid buying someone else’s $50,000 problem.

​Thinking of buying in the GTA? Contact me today!

From Loan to Home — Your Trusted Path to Ownership. 🏡

Read

Protecting Your Future: What Every Ontarian Needs to Know About "Matrimonial Home" Law

​No one enters a marriage or a new chapter of life expecting it to end. It is a sensitive topic, and honestly, it’s not a situation I would ever wish for any of my clients or friends to go through.

​However, part of being a responsible homeowner and a savvy investor is being knowledgeable. In Ontario, the laws surrounding the family home are unique and can be quite surprising if you aren't prepared. Whether you’re a first-time buyer, a parent helping your children with a down payment, or someone bringing a home into a new marriage, understanding these rules is a vital part of protecting your hard-earned equity.

​The Concept of the "Matrimonial Home"

​In Ontario, the Family Law Act gives a "special status" to the home where a married couple "ordinarily resides." This isn't just about whose name is on the deed; it’s about the legal right to the value of the roof over your head.

​The Key Takeaway: Even if you owned your home long before the wedding, the moment it becomes the "Matrimonial Home," your spouse likely has an equal right to stay there and a claim to half its value.

​The 50/50 Rule: The Exception That Costs Thousands

​In most Ontario property divisions (called Equalization), you generally get to keep the value of what you brought into the marriage and only split the growth that happened while you were together. The Matrimonial Home is the major exception to this rule.

​The Math That Matters:

  • ​The Scenario: You own a condo worth $600,000 on your wedding day.

  • ​The Reality: If that condo becomes your matrimonial home and you later separate, you generally cannot deduct that initial $600,000 as a pre-marriage asset.

  • ​The Result: The entire value of the home is included in the 50/50 split. Without a legal agreement, you could lose half of your pre-marriage equity.

​Married vs. Common-Law: Know the Difference

​There is a massive misconception that common-law partners have the same rights as married couples. In Ontario, they do not.

  • ​Married Couples: Have automatic equal rights to the value and possession of the home, regardless of who is on the title.

  • ​Common-Law Couples: Do not have these automatic rights. Generally, ownership follows the name on the title, though a partner may attempt to prove a legal claim (like a "constructive trust") if they contributed to the property.

​A Note for Parents: The "Gifted" Down Payment

​With the current market in the Greater Toronto Area, I see many wonderful parents gifting large sums to help their children buy a home. It’s a beautiful gesture, but without a formal legal agreement, that gift becomes a shared family asset the moment the child marries.

​If your intent is for that money to stay with your child, being proactive is the kindest thing you can do for their financial future.

​How to Protect Your Equity

  1. ​Marriage Contract (Prenup): A legal document that specifically excludes the home or the gifted funds from the equalization process.

  2. ​Deed of Trust: Formally documents who provided the funds and their share of ownership.

  3. ​Loan Agreement: Treating the down payment as a registered loan rather than an outright gift.

​Your Homeowner Checklist

  • ​[ ] Verify Title: Confirm exactly whose name is on the property deed.

  • ​[ ] Identify Status: Are you legally married or in a common-law partnership?

  • ​[ ] Benchmark Value: Keep a professional appraisal of the home’s value on your wedding date.

  • ​[ ] Seek Legal Counsel: Consult a family lawyer to discuss a domestic contract.

​Bottom Line

​Your home is likely your biggest investment. Protecting it requires more than just a good mortgage rate or a high sale price—it requires a clear understanding of the law. A quick conversation today can protect your equity for the long term.

​Disclaimer: This article is for informational and educational purposes only and does not constitute legal or financial advice. Real estate and family laws in Ontario are complex and subject to change. As a Real Estate Sales Representative and Mortgage Agent, my expertise lies in property transactions and financing; however, I am not a lawyer. Every individual situation is unique, and I strongly recommend consulting with a qualified family law professional and a tax advisor to discuss your specific circumstances and legal rights. Information regarding the Family Law Act and property division should always be verified by legal counsel.

From Loan to Home — Your Trusted Path to Ownership. 🏡

Read
This website may only be used by consumers that have a bona fide interest in the purchase, sale, or lease of real estate of the type being offered via the website. The data relating to real estate on this website comes in part from the MLS® Reciprocity program of the PropTx MLS®. The data is deemed reliable but is not guaranteed to be accurate.